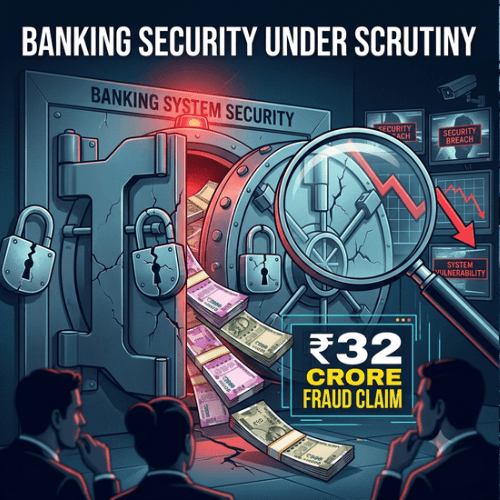
A disputed ₹32 crore cyber fraud allegation involving YES BANK has renewed concerns about cybersecurity preparedness, financial accountability, and the resilience of India's rapidly expanding digital banking infrastructure.
According to a November 13 report cited by The420.in, YES BANK allegedly suffered losses involving government accounts, raising questions about safeguards protecting sensitive financial transactions and public funds.
However, YES BANK strongly denied the allegations, maintaining that no government accounts were compromised, its systems remained secure, and no financial losses occurred. The alleged breach remains unverified.
The controversy comes amid other reported financial security incidents. Central Bank of India was associated with approximately ₹13.97 crore in unauthorized transactions, highlighting concerns surrounding transaction authentication and monitoring.
Similarly, Spandana Sphoorty reportedly experienced ₹7.8 crore in unauthorized transfers across 82 transactions, while SG Finserve disclosed ₹5.1 crore in unauthorized payments involving banking application programming interfaces.
Although these incidents differ in circumstances, they expose broader concerns about payment authorization, API security, privileged access controls, and the effectiveness of real-time fraud detection mechanisms.
India's banking ecosystem increasingly relies on interconnected digital platforms, including RTGS, IMPS, corporate banking applications, and automated payment interfaces. Such integration demands continuous monitoring and stronger authentication safeguards.
Industry experts emphasize the importance of Zero Trust architectures, behavioral analytics, AI-powered anomaly detection, multifactor authentication, independent security audits, and automated alerts for suspicious high-value transactions.
Equally important is institutional accountability. Regulators, banks, and financial institutions must strengthen incident disclosure, forensic investigation, fund recovery mechanisms, and coordination to ensure that security failures are identified and addressed promptly.
The bigger question is whether banks apply the same rigor to securing customer funds as they demand through customer KYC compliance. India's digital banking credibility ultimately depends on proactive fraud prevention, transparent governance, and demonstrable cybersecurity resilience—not merely regulatory compliance or investments in security technology.