By Deepak Mishra, CEO, Prodevans Technologies
India has built one of the world’s most successful real-time payment ecosystems. The next challenge is not merely how to fund UPI at scale, but whether India can use the Digital Rupee to create a complementary, sovereign, low-cost settlement layer for the next phase of digital inclusion.
India stands at a crossroads in its digital transformation journey. In recent months, I have observed—and actively participated in—the vigorous debate around what many in the industry now describe as “UPI MDR 2.0”. At the heart of that debate lies a difficult policy and commercial question: how do we continue to scale a national payment infrastructure while ensuring that the smallest merchants, informal businesses and inclusion points are not priced out of the digital economy?
The Reserve Bank of India (RBI), the National Payments Corporation of India (NPCI), banks, fintech companies and payment service providers are all confronting the same reality. UPI has become a critical national digital infrastructure, but infrastructure at this scale requires continuous investment in resilience, cybersecurity, fraud prevention, customer service and innovation.
NPCI’s FAQ dated 15 September 2026 states that a Merchant Discount Rate (MDR) of 0.4% will apply to select Person-to-Merchant (P2M) UPI transactions above ₹2,000, with a cap of ₹300 for transactions of ₹75,000 and above. The framework is scheduled to take effect from 15 October 2026. Small merchants operating under the P2PM framework and receiving up to ₹1 lakh per month through UPI QR remain protected by zero MDR.
This is an understandable attempt to balance sustainability and inclusion. But it should not be mistaken for the final destination. The introduction of selective MDR is also a signal: the economics of India’s existing digital payment model are entering a new phase, and incremental optimisation alone may not be enough for the decades ahead.
The question is no longer only “What should UPI MDR be?” The larger question is: “What should India’s next-generation digital-money architecture look like?”
The MDR 2.0 Dilemma: Scale Has a Cost
UPI has transformed how India pays. In August 2026 alone, NPCI reported roughly 2,451 crore UPI transactions valued at about ₹29.9 lakh crore. That scale is extraordinary, but it also demands massive physical and digital infrastructure: data centres, network capacity, transaction switching, banking systems, security operations, reconciliation, fraud controls and customer support.
NPCI’s own policy note explains that MDR revenue is intended to be distributed within the UPI ecosystem to support infrastructure resiliency, innovation, cybersecurity and customer service. That is a legitimate economic requirement. Someone must fund the systems that make billions of transactions appear instant, simple and dependable to the end user.
The problem is where that cost ultimately lands. If the merchant bears too much of it, adoption—especially among smaller businesses—can suffer. If banks, fintech firms or the public exchequer absorb the cost indefinitely, questions arise about sustainability and investment capacity. Thresholds, exemptions, caps and cross-subsidies can soften this tension, but they cannot make the underlying economics disappear.
This is why we should be careful not to treat MDR reform as the endpoint of India’s payment innovation. We are attempting to optimise the economics of a payment rail built around commercial bank money. A more fundamental option is already available: sovereign digital money itself.
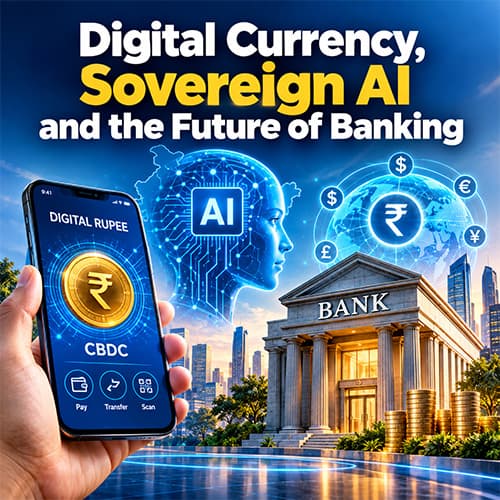
The CBDC Difference: UPI Moves Money; e₹ Is Money
The most important distinction in this debate is conceptual. UPI is a means of payment. The Digital Rupee, or e₹, is the digital form of the Indian Rupee issued by the RBI. It is legal tender and a liability of the central bank. RBI’s own FAQs make this distinction explicit.
That difference matters architecturally. In a native CBDC transaction using a CBDC QR, RBI states that P2P and P2M transactions occur between two e₹ wallets and settle instantaneously without passing through the users’ bank accounts. By contrast, when an e₹ app scans a UPI QR, settlement follows UPI settlement timelines. The two experiences can look similar to the customer, but the settlement logic underneath them is not identical.
UPI is a payment mechanism. The e₹ is sovereign money. That distinction creates a new policy and architecture option for India.
This does not mean that every intermediary disappears. RBI’s retail CBDC pilot is currently distributed through participating banks and non-banks, which provide wallets, onboarding, support and access. Technology, compliance, cyber defence and customer service still cost money. CBDC should therefore not be portrayed as a “free” system with no operating expenses.
What changes is the nature of the settlement asset. Instead of every digital retail payment ultimately being an instruction to move commercial-bank deposits, a native e₹ payment can transfer central-bank money itself. That can simplify some settlement layers and create a stronger foundation for cash-like digital payments.
Can the e₹ Create a True Zero-MDR Option?
The answer should be framed carefully: zero MDR is not an automatic technological property of CBDC. It is a policy choice that CBDC makes possible.
At present, RBI states that there are no charges or fees associated with using e₹ or e₹ wallets during the pilot. That is important, but a pilot pricing model is not the same as a permanent national commercial framework. If India wants the Digital Rupee to become the digital equivalent of cash for everyday merchant payments, the RBI and the wider ecosystem could explicitly preserve a zero-percentage-MDR layer for basic e₹ transactions while allowing commercial pricing for value-added services around it.
Such a design would mirror an important characteristic of physical cash: the merchant does not surrender a percentage of every banknote received. The public sector already bears significant costs to issue, distribute and secure physical currency because cash is a foundational public good. A carefully designed e₹ framework could extend part of that public-good logic into the digital domain.
The policy objective should therefore not be to eliminate banks, fintech firms or payment companies. They remain essential to distribution, innovation, user experience, merchant services, cybersecurity and support. The objective should be to separate the cost of basic sovereign-money transfer from the pricing of optional commercial services layered around it.
Zero MDR is not an automatic feature of CBDC. It can, however, be a deliberate national policy feature of a digital-cash architecture.
UPI and CBDC Should Complement Each Other
The debate must not become “UPI versus e₹”. That would be a false choice. India has already built a pathway for interoperability. RBI allows e₹ wallets to scan UPI QR codes, giving CBDC access to the country’s vast merchant acceptance infrastructure. This is strategically important because it reduces one of the hardest barriers faced by any new payment instrument: merchant acceptance.
UPI can continue to flourish as the country’s universal payment interface and innovation layer. The e₹ can increasingly serve as a sovereign settlement asset for use cases where cash-like finality, programmability or offline capability are valuable. In other words, UPI can remain the interface that citizens know, while CBDC can become an additional form of digital value underneath selected transactions.
This combination could be more powerful than either system in isolation. India does not need to dismantle its successful payment architecture to advance CBDC. It can use UPI’s ubiquity to accelerate CBDC adoption while using e₹ to extend the design space of digital payments.
Beyond MDR: The Strategic Value of Programmable and Offline Money
The case for e₹ is larger than transaction pricing. RBI is already testing programmability and offline functionality. Programmability can allow a sponsor—such as a government department or corporation—to ensure that digital funds are used for a defined purpose, based on parameters such as expiry, geography or merchant category. Offline features are being explored for environments with limited or no internet connectivity.
These capabilities create possibilities for targeted Direct Benefit Transfers, defined-purpose government subsidies, employee allowances, specialised lending programmes and payments in remote areas. They also raise legitimate questions around privacy, user choice, cybersecurity, operational resilience and governance. Those questions must be addressed transparently as the architecture scales.
The broader point is that CBDC is not simply another payment app. It is a new monetary infrastructure. The more India develops it as a reliable, interoperable and trusted public platform, the less the national debate needs to be trapped within a single question about how to price an existing payment rail.
The Call to Action: Move from Pilot Thinking to Infrastructure Thinking
RBI and NPCI deserve enormous credit for what UPI has achieved. It has changed consumer behaviour, expanded merchant acceptance and demonstrated that India can build digital infrastructure at population scale. The introduction of a selective MDR framework should be viewed not as a failure of UPI, but as evidence that UPI has matured into infrastructure whose economics now need to be made durable.
The next step should be equally ambitious. India should accelerate the Digital Rupee from a controlled pilot mindset toward a clearly defined national infrastructure roadmap—without compromising the testing, safeguards and phased implementation that central-bank money demands.
That roadmap should answer a set of practical questions: How quickly can e₹ scale? How should native CBDC QR and UPI QR experiences converge? What is the long-term economic model for banks and non-banks distributing wallets? How will privacy and fraud controls evolve? What service-level standards will apply? How will offline transactions be secured? And can the country preserve a basic e₹ merchant-payment layer that remains free of percentage-based MDR?
These questions are more consequential than another round of threshold optimisation. They determine whether India remains primarily a leader in digital payments—or becomes a leader in sovereign digital money as well.
At Prodevans Technologies, our work across high-volume banking, infrastructure and digital platforms has reinforced one lesson repeatedly: transformation succeeds when technology architecture, operating economics and public policy are aligned. India has already proved that it can build at unprecedented scale. The challenge now is to make the next layer as intuitive, resilient and inclusive as UPI became.
The Next Digital India Leap
The next great chapter of Digital India should not be limited to deciding who pays 0.4%, who qualifies for an exemption or where a transaction threshold should sit. Those are important operational decisions, but they are not the final frontier.
The real frontier is the convergence of payment infrastructure and sovereign digital currency. UPI has given India a universal digital payment interface. The e₹ can give India a universal digital form of sovereign money.
The policy ambition should therefore be clear: let UPI continue to grow as the country’s most successful payment rail, while building the Digital Rupee into its complementary sovereign-money layer—interoperable, scalable, resilient, inclusive and capable of offering citizens and merchants a genuine digital-cash experience.
MDR 2.0 may help sustain today’s ecosystem. The e₹ should be designed for tomorrow’s.