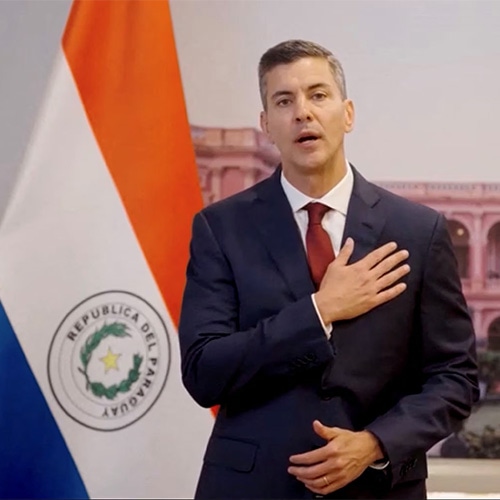
A banking failure has escalated into a national political crisis in Paraguay, bringing down President Santiago Peña and exposing the dangerous consequences of weak financial oversight, alleged political influence and the misuse of public trust.
The collapse of digital lender Ueno Bank has triggered mass protests, frozen customer accounts, prompted criminal investigations and shaken confidence in the country's financial institutions. On 6 November, Paraguay's Senate unanimously impeached Peña, and Vice President Pedro Alliana was sworn in as president. Peña, who denies wrongdoing, was subsequently placed under house arrest.
The crisis raises an uncomfortable question for governments, regulators and banking institutions worldwide: When a bank becomes too politically connected to fail, who protects the depositors?
The rise and collapse of Ueno Bank
Ueno, a fast-growing digital bank, reported approximately three million customers and held more than $800 million in public deposits. Regulators intervened after identifying serious capital deficiencies and concerns about lending to companies connected with its controlling shareholder, Grupo Vázquez.
From frozen savings to political upheaval
The intervention disrupted access to deposits and payments. Allegations involving political connections, pension funds and regulatory failures intensified public anger. Peña announced his resignation on 5 November, but lawmakers proceeded with impeachment rather than accepting his departure.
The deeper crisis: When banking, politics and public money collide
The central issue is not simply that a digital bank failed. It is how a financial institution with substantial public-sector deposits could experience such severe solvency problems while operating under regulatory supervision.
Ueno reportedly held approximately $380 million from Paraguay's state pension and health fund. Questions have emerged over related-party lending, the quality of reported assets and whether regulators responded adequately to warning signs. These are allegations and matters under investigation, not established findings of criminal responsibility.
The political controversy intensified because Peña previously held shares in Grupo Vázquez, the business group associated with the bank. He maintains that he sold his holdings in March 2025 and denies improper involvement. The former central bank governor, Carlos Carvallo, had previously led Ueno's predecessor, raising further questions about regulatory independence.
The immediate financial damage has extended beyond shareholders. Depositors have faced restricted access to their money, businesses have encountered payment disruptions, and pensioners have been caught in the uncertainty. Authorities have begun releasing some funds, while deposit insurance is expected to protect an estimated 97% of customers, although protection limits and repayment timing matter.
This illustrates a fundamental distinction: a bank can be technologically sophisticated and commercially successful while remaining financially fragile.
Seven lessons every country must learn
1. Regulatory independence is non-negotiable
Central banks and financial supervisors must operate without political interference. Any conflict involving bank owners, senior regulators or public officials requires disclosure, independent scrutiny and appropriate recusal.
2. Public deposits demand stronger safeguards
Pension funds, social-security contributions and government deposits should face strict concentration limits, transparent allocation rules and continuous risk monitoring. Public money must never become an informal rescue mechanism for politically connected institutions.
3. Rapid digital growth does not guarantee financial stability
Millions of customers and an attractive banking application cannot compensate for inadequate capital, poor asset quality or weak lending controls. Digital banks require the same prudential discipline as traditional banks.
4. Connected lending must be continuously monitored
Loans involving shareholders, directors and related businesses deserve enhanced scrutiny. Regulators should examine beneficial ownership, unusual exposure concentrations and transactions that may conceal financial weakness.
5. Depositor protection must work during a crisis
Deposit insurance is only effective when customers understand their coverage and can access protected funds promptly. Resolution plans should preserve essential payment services wherever possible.
6. AI-driven supervision can strengthen early warnings
Advanced analytics can help identify suspicious transactions, related-party exposures, abnormal liquidity movements and inconsistencies in financial reporting. However, technology cannot replace independent audits, sound governance or decisive regulatory action.
7. Financial transparency is essential to political stability
When public officials, regulators and financial institutions become entangled, a bank failure can escalate into a constitutional crisis. Transparent investigations, accountable leadership and credible enforcement are essential to restoring confidence.
Paraguay has faced banking failures before
The latest collapse also raises questions about whether Paraguay has fully absorbed the lessons of its earlier financial crises.
According to an International Monetary Fund analysis, between 1995 and 2003 Paraguay experienced repeated banking crises in which more than half its banks and two-thirds of its nonbank financial institutions were closed or liquidated. The cumulative direct fiscal and quasi-fiscal costs exceeded 16% of GDP.
The IMF identified weak supervision, connected lending, rapid financial liberalisation and delayed regulatory intervention as important contributing factors.
The parallels with today's allegations are concerning. They suggest that technological modernisation alone cannot eliminate longstanding governance vulnerabilities.
What India and other emerging economies should learn
For India, the Paraguay episode is particularly relevant as banks, fintech companies, digital lenders and payment platforms expand rapidly.
India's banking framework includes RBI supervision, deposit insurance and prudential requirements, but financial resilience demands continuous vigilance.
The most important priorities include strengthening related-party exposure monitoring, ensuring transparent deployment of public funds, conducting independent stress tests, improving early-warning systems and maintaining operational continuity during bank failures.
Banks should also distinguish between cybersecurity, financial integrity and governance risk. Strong authentication and sophisticated fraud detection cannot compensate for concealed losses or inadequate capital.
The larger warning: A banking failure can become a crisis of democracy
Paraguay demonstrates how quickly financial instability can undermine political legitimacy when public money, institutional credibility and citizens' savings are simultaneously at risk.
The collapse of Ueno Bank should not automatically be interpreted as proof that Paraguay's entire banking system is insolvent. Authorities maintain that the immediate crisis is concentrated in Ueno, although the wider economic and political consequences remain uncertain.
The critical test now is whether the new administration can protect depositors, establish accountability, restore confidence in independent supervision and prevent the crisis from spreading.
The greatest threat to a banking system is not always a cyberattack, a liquidity shortage or a market crash. Sometimes, it is the erosion of institutional integrity from within.
Paraguay's experience offers a universal lesson: when financial governance fails, the consequences can reach far beyond banking—threatening public confidence, economic stability and even the survival of governments.